Insurers lean on Wolters Kluwer Insurance resources for the unglamorous but critical work of knowing what the rules say: regulatory and compliance research, legal and tax reference material, and forms and content resources that help product, legal and compliance teams track what must be said, where, and from when. The difficulty rarely sits in the research itself. It sits in the distance between an authoritative piece of source content and the thousands of policy packets, endorsements, notices and claims letters that must reflect it accurately, on time, in every state, province or region where you write business. When that distance is bridged by spreadsheets, side-by-side screens and developer tickets, regulatory change becomes a project rather than a routine, and operational agility quietly erodes.
TL;DR
- Wolters Kluwer Insurance content sits upstream of production: it informs what wording, disclosures and forms are required, but it is not itself a document generation engine, and licensed material does not flow automatically into customer-facing output.
- The practical gap is the governed hand-off: research → approved clause language → versioned template → assembled document → approval → delivery → archive → evidence.
- Document complexity in insurance is driven by jurisdiction, product, form edition, effective date, language, brand and data drawn from several systems of record at once.
- Experlogix Document Automation is commonly positioned as a complementary document layer alongside core, agency, rating and content systems, with Microsoft Word-based templates business users maintain, business rules that apply jurisdiction-specific language and disclosures, audit trails covering edits, approvals and timestamps, and an API for integration with existing applications.
- AI can accelerate drafting, review and workflow assembly, but regulated judgement — what wording is required, what coverage applies — stays with authorised people and systems, inside logged, governed workflows.
Happy shiny people. The industry loves to show policyholders living their best lives — untroubled, unbothered, protected from the catastrophes you underwrite — and a centrally managed document automation layer that lets business teams implement wording changes accurately and quickly, without a heavy ongoing IT lift, lets the insurance professionals behind the scenes live rather well too.
What Wolters Kluwer Insurance Actually Owns in the Document Lifecycle
Answering the central question directly: Wolters Kluwer Insurance resources are an authority on what the content should say and why, not a document automation engine producing the documents your policyholders receive. In the lifecycle terms most insurance operations leaders use, it is an upstream source of truth for regulatory and compliance intelligence and reference content, feeding the decisions that product, legal and compliance teams make about forms, disclosures and wording.
That distinction matters because the four artefacts in the chain are routinely conflated:
- Research and reference material Regulatory tracking, legal and compliance commentary, bulletins and analysis that tell you a requirement exists or has changed.
- Licensed source content Material supplied under a licence, with terms governing how it may be stored, reproduced or distributed.
- Approved clause language Your organisation’s own wording, reviewed and signed off internally, which may be informed by research and by filed forms.
- Generated output The declaration, endorsement, notice or letter the policyholder, broker or regulator actually receives.
Nothing moves automatically between those four. A bulletin does not become an approved clause. An approved clause does not become a template. A template does not become a filed, delivered, retained document. Each transition is a governance decision with an owner, and the health of your document operations depends on whether those transitions are explicit and recorded, or informal and remembered.
Why licensing deserves its own answer
Reference and forms content is typically licensed with conditions on reproduction and redistribution. Before any wording derived from licensed material enters a production template estate, confirm with your legal team and the content provider what may be copied verbatim, what must be paraphrased or internally drafted, and how attribution and retention are handled. This is a contractual question, not a technical one, and a document platform cannot answer it for you — it can only enforce the answer once you have it.
Where Document Complexity Emerges Around Insurance Content Sources
Regulatory change is the obvious trigger, but the complexity compounds along several dimensions simultaneously.
Jurisdiction. The same product line can require different notices, different mandatory wording and different formatting by state, province or region. One notice change in a handful of jurisdictions can touch dozens of templates if wording has been copied into each one rather than centralised as a reusable clause — which is why streamlining regulatory documents with automation starts with where the wording lives.
Form edition and effective date. A document reproduced years later — for a coverage dispute, an audit, a regulatory enquiry or litigation support — must reflect the edition and wording in force at the time, not today’s. That requires effective-dated content and template versioning, not simply the latest file.
Product variation. Endorsement schedules, optional coverages, deductible structures and class-specific language multiply conditional paths within a single packet.
Data from several systems at once. A policy packet may need policy and coverage data from the policy administration system, client and producer context from the agency management system, billing terms from the billing system, and clause content from a governed content repository. Source data is rarely output as-is: nested structures need unpacking, values need calculating, formatting and look-ups, and conditional logic decides which sections appear at all. Historically that logic is where developers and consultants get written into the critical path.
Volume and timing. Renewal cycles, mass endorsements following a regulatory change, and catastrophe communications all produce peaks that behave nothing like day-to-day interactive generation. They need batch behaviour, retry handling and reconciliation, not just a working template.
Language and accessibility. Preferred-language output, accessible PDF or HTML, print, email, portal and e-signature channels each carry their own requirements and their own proof-of-delivery expectations.
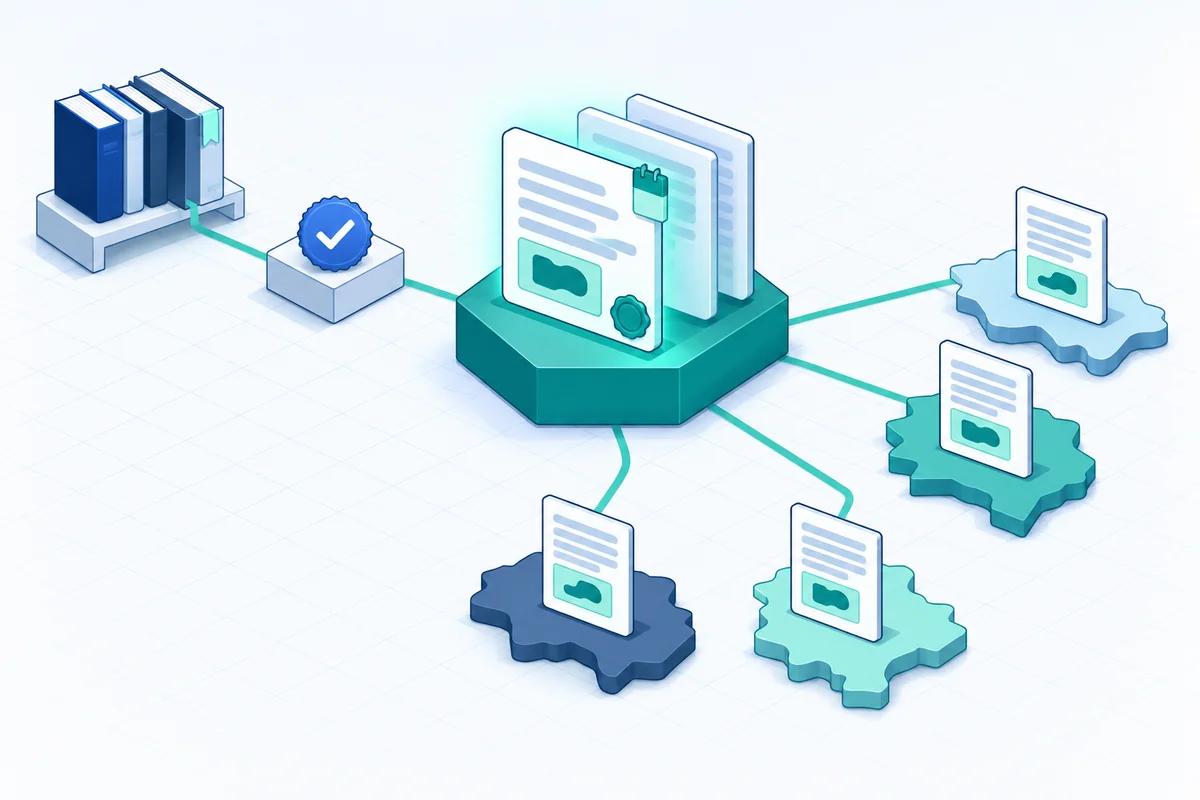
Change the clause once. Every template follows.
One approved clause, referenced by every template
Document Workflows Across the Insurance Lifecycle
Mapping where content-driven wording actually lands helps size the problem honestly:
Every one of these is a candidate for a controlled clause library. Each is also a potential point of divergence if wording is maintained independently in multiple systems. For a closer look at high-impact candidates, see these essential workflows for smarter insurance document automation.
- New business and quoting — applications, proposals, quote letters, product disclosures, required pre-sale notices.
- Issuance — policy packets, declarations, master policies, evidence of coverage, certificates, ID cards, schedules of forms.
- Endorsements — change confirmations, revised declarations, endorsement wording with its own edition and effective date.
- Billing — invoices, instalment schedules, premium increase notices, cancellation and lapse notices with statutory timing rules.
- Renewal — renewal packages, non-renewal notices, rate change explanations, updated disclosures.
- Claims — acknowledgements, reservation of rights letters, status updates, settlement and denial correspondence, benefit communications.
- Audit and compliance — premium audit reports, tax forms, statutory and regulatory reporting, actuarial memoranda, state, provincial or regional filing packages.
- Distribution servicing — producer and broker packets, appointment and onboarding documents, commission statements.
Native Platform Output Versus a Governed Document Layer
Most insurers already have document capability somewhere — correspondence in the core platform, merge templates in the agency management system, proposal output from a rating or quoting tool. Those capabilities are real and often the right home for tightly coupled, transaction-specific output.
The practical boundary question is not “which tool is better”, it is “where does each document belong?” A reasonable test:
When the document depends overwhelmingly on one system’s data, changes rarely, and the platform’s own templating is comfortably maintained by your team.
When the document draws on several systems, carries heavy conditional logic, must be versioned by jurisdiction and effective date, needs approval routing and delivery evidence, or must look and read identically regardless of which system triggered it.
A governed document layer centralises templates, clause libraries, branding, rules, approvals, delivery and archiving in one place, so that a regulatory wording change is made once and applies across every platform that requests a document — the core idea behind automating document generation across your enterprise systems. That is one architectural option among several, and it earns its place only when the multi-system, multi-jurisdiction pattern is genuinely present.
How Experlogix Document Automation Fits Alongside Wolters Kluwer Insurance Content
Experlogix Document Automation for insurance is deployed alongside existing insurance technology rather than in place of it. In this context it sits downstream of your content and compliance sources and across your systems of record, acting as the production and governance layer for the documents themselves.
Capabilities relevant to a content-driven estate include:
- A Microsoft Word-based template builder using familiar Word functionality, so business users can build and maintain templates — including dynamic data fields, jurisdiction-specific content, dynamic tables and graphics, and automatic language selection — without coding and without maintaining separate template versions by hand.
- Content Manager, a secure, structured repository for digital assets such as PDF forms, documents, logos, images and multimedia, using a folder-like structure with search, linked metadata forms, field mapping and version control. This is the natural home for approved clause and form assets, tagged with the metadata that drives correct selection.
- Smart Flows for automated document flows, with a low-code, drag-and-drop workflow builder for routing, approvals and downstream steps.
- Smart Forms for structured data capture where the data you need does not already exist in a core or CRM system — a form link in a workflow, completion triggering document generation.
- Connection to an unlimited number of data sources, with out-of-the-box integration to major business platforms including Microsoft Dynamics 365 and Salesforce, plus integration with storage and e-signature steps in the wider flow.
- The Experlogix Document Automation API, with role-based API keys, an extensive library of API calls and programmable functionality, allowing document generation and automation to be embedded in virtually any application.
- Audit trails in which edits, approvals and timestamps are logged, supporting a regulator-ready record, with metadata tagging and automated archiving to retrieve documents during audits.
- Security practices aligned with SOC 2, with industry standards such as NIST and OWASP followed in the company’s security approach.
In a content-provider context, the pattern is straightforward: research and regulatory intelligence informs a human decision about wording; the approved clause is stored once, versioned and effective-dated; templates reference the clause rather than duplicating it; and generation requests arriving from any platform produce the same compliant output.
Integration Architecture, Without the Mystique
API-led integration is the architectural backbone here, and it is a strength rather than a compromise. A well-specified API integration is a one-time design exercise that then carries years of change: new products, new jurisdictions, new triggering systems, growing volumes and longer document packets all flow through the same contract.
Framed as business enablement: IT designs and secures this once, then operations and compliance own the wording, the rules and the approvals thereafter.
What to specify once, carefully:
- Data contract — which fields, in which structures, with which types; how nested data is unpacked; how calculations and look-ups are handled; what happens when a value is missing.
- Identity and access — service identities, role-based keys, least privilege, and clear separation between environments.
- Trigger design — which events generate synchronously, which queue, which run scheduled or in batch; renewal peaks and mass endorsements belong in the latter categories.
- Idempotency and failure handling — duplicate events, retries, partial batches, delivery failures and write-back errors all need defined behaviour and a reconciliation path.
- Observability — monitoring, alerting, and the evidence record proving which template version, which data, which approver, which delivery channel and which retention rule applied.
- Write-back — status, document reference and archive location returned to the triggering system so the system of record stays authoritative.
Business Ownership: Who Owns What
A clean responsibility map prevents most document disputes before they happen.
- Product, legal and compliance Own wording, clause approval, jurisdiction applicability, form edition and effective date.
- Operations Own templates, workflow configuration, approval routing, exception handling and delivery preferences.
- IT and security Own integration, identity, environments, monitoring and release control.
- Source system, document layer and archive The source system owns the data; the document layer owns assembly, governance and evidence; the archive owns retention.
Low-code configuration and Word-based authoring matter because they move template maintenance from the development backlog to the team that understands the requirement — while IT retains control of data, security and releases. That is the trade-off worth being explicit about: business ownership is a governance model, not an absence of governance. Without clause-level reuse, version control and approval routing, decentralised authoring simply distributes the version-control problem more widely.
AI, Governance and the Research-to-Production Gap
AI is genuinely useful in this chain, and genuinely constrained by it.
Useful: summarising lengthy regulatory material for a human reviewer; drafting a candidate clause for legal to approve; comparing a proposed template change against the current approved version; assembling a first-pass workflow that an operations lead then refines; flagging inconsistencies across a template estate for human attention. Experlogix positions AI capability inside defined parameters, with agent actions logged and documents traceable, and the Smart Flows MCP (Model Context Protocol) server is designed to let AI agents execute document automation workflows with governance applied and results returned — the agent invokes an approved workflow rather than improvising a document.
Constrained: AI should not decide what wording a jurisdiction requires, whether coverage applies, how a claim is resolved, or what a filed form says. Those remain decisions for authorised people and systems. A sensible rule for a content-driven estate is that AI may propose and may initiate an approved workflow, but only a human approver can move content from candidate to approved, and every such transition is logged.
Summary
Wolters Kluwer Insurance resources answer the question of what your documents must say. Your document operations answer the question of whether what they must say actually, reliably, reaches the page — in every jurisdiction, at every effective date, across every system that triggers a document.
The useful work for most insurers is in the middle: making the hand-off from research to licensed material to approved clause to template to generated output explicit, owned and evidenced. Centralising clause content and template governance, deciding deliberately which documents stay native and which justify a dedicated layer, specifying the API data contract and failure behaviour once, and keeping regulated judgement with authorised people are the four moves that pay off repeatedly as products, jurisdictions and volumes grow.
Reasonable next steps are unglamorous and effective: inventory your templates and identify where the same wording is duplicated; confirm licensing terms for any externally sourced content before it enters production; name the owner for each stage of the research-to-production chain; and test your estate against a realistic scenario — a multi-jurisdiction wording change applied mid-renewal cycle — to see how long it takes and how many people it needs. The answer to that test tells you more about your document operations than any feature list will.
Frequently Asked Questions
What role does Wolters Kluwer play, and where does document production begin?
Answering the central question directly: Wolters Kluwer Insurance resources are an authority on what the content should say and why , not a document automation engine producing the documents your policyholders receive . In the lifecycle terms most insurance operations leaders use, it is an upstream source of truth for regulatory and compliance intelligence and reference content, feeding the decisions that product, legal and compliance teams make about forms, disclosures and wording.
Where does insurance document complexity arise around Wolters Kluwer?
Regulatory change is the obvious trigger, but the complexity compounds along several dimensions simultaneously. Jurisdiction. The same product line can require different notices, different mandatory wording and different formatting by state, province or region. One notice change in a handful of jurisdictions can touch dozens of templates if wording has been copied into each one rather than centralised as a reusable clause — which is why streamlining regulatory documents with automation starts with where the wording lives.
When is native document output enough alongside Wolters Kluwer?
Most insurers already have document capability somewhere — correspondence in the core platform, merge templates in the agency management system, proposal output from a rating or quoting tool. Those capabilities are real and often the right home for tightly coupled, transaction-specific output.
How should a governed document layer connect with Wolters Kluwer?
API-led integration is the architectural backbone here, and it is a strength rather than a compromise. A well-specified API integration is a one-time design exercise that then carries years of change: new products, new jurisdictions, new triggering systems, growing volumes and longer document packets all flow through the same contract.
Who should own document templates, approvals and governed changes?
A clean responsibility map prevents most document disputes before they happen. Product, legal and compliance Own wording, clause approval, jurisdiction applicability, form edition and effective date. Operations Own templates, workflow configuration, approval routing, exception handling and delivery preferences. IT and security Own integration, identity, environments, monitoring and release control.
Turn approved wording into compliant insurance documents
See how Experlogix Document Automation helps insurers manage jurisdiction-specific content in Word-based templates, route approvals and keep an audit trail across policy, claims and customer communications.