National Underwriter has long occupied a particular shelf in the insurance profession — the one you reach for when a coverage question has no obvious answer. Its reference works, coverage interpretation material, and professional publications help underwriters, claims professionals, and compliance teams reason about what a form actually does. What that research cannot do is push the resulting wording into a declaration page, a reservation of rights letter, or a renewal packet. That handoff — from authoritative interpretation to approved, effective-dated, auditable production wording — is where most insurers still rely on manual rekeying, long email chains, and a developer or consultant queue.
TL;DR
- National Underwriter and similar insurance reference and content providers are authoritative sources for coverage interpretation, commentary, and professional education — they are not document production systems, and treating them as one creates silent compliance risk.
- The real gap sits between research (what a clause means), approved wording (what legal and compliance have sanctioned for production), templates (where that wording lives with its logic), and output (the document a policyholder, broker, or regulator actually receives).
- Document complexity in this chain comes from jurisdiction variation across states, provinces, and regions, product variants, form editions, effective dates, language preferences, and data drawn from several systems of record at once.
- A governed document layer — such as Experlogix Document Automation — lets operations and compliance teams own templates and clause libraries in familiar Microsoft Word tooling, while IT retains control of integration, identity, environments, and releases.
- Licensing matters: reference content is generally licensed for research and professional use, so the route from a published commentary to production policy language runs through your own legal and compliance approval, not through copy and paste.
Happy shiny people. The industry loves to picture policyholders living their best lives, blissfully unbothered by the catastrophes their cover quietly absorbs; a centralised document layer that lets business teams manage document automation accurately and quickly, without heavy ongoing IT labour, lets the insurance professionals behind those policies live rather well too.
What National Underwriter Actually Owns in the Insurance Workflow
National Underwriter sits in the insurance forms and content provider category alongside other research and reference sources that insurance professionals consult daily. Its role is interpretive and educational: helping property and casualty, life, and health professionals understand coverage questions, claims scenarios, regulatory developments, and market practice. Teams typically reach this material through digital reference libraries rather than through a policy administration system (PAS) or agency management system (AMS).
That distinction is more than semantic. A reference library is a source of understanding. A PAS, AMS, or claims system is a system of record. A document automation platform is a production layer. Each has a different owner, a different change cycle, and a different audit obligation. Articles about document automation often blur these together, and that blurring is exactly how an insurer ends up with a claims letter quoting commentary that was never approved for customer-facing use.
So before any automation discussion, three questions are worth answering explicitly:
- Which system holds the authoritative data for this document — policy, billing, claim, producer, or benefit state?
- Which team holds the authoritative wording — and what approval step converts interpretation into production language?
- Which platform holds the template, the assembly logic, the delivery evidence, and the retained artefact?
National Underwriter answers none of these three. It informs the second one. That is a feature, not a shortcoming.
Where the Research-to-Production Gap Causes Real Pain

Consider a workers’ compensation endorsement question, a flood exclusion interpretation, or a change in how a cancellation notice must be worded in a particular state or province. A compliance analyst researches the question, forms a view, and drafts revised language. What happens next is where many insurers lose weeks.
In a traditional architecture, that revised language has to be reproduced in several places: the core platform’s native correspondence templates, a few spreadsheet-managed Word files used by claims, a broker-facing proposal template in the agency system, and perhaps a legacy document tool supporting a closed book of business. Each copy has its own version history, its own owner, and its own chance of being missed. The analyst’s careful work becomes a change request, and the change request joins a development backlog.
The operational symptoms are familiar:
- Inconsistent wording across channels for the same regulatory obligation.
- Edition and effective-date drift, where a document reproduced two years later uses today’s wording rather than the wording in force at the time.
- Approval opacity, where no one can demonstrate who signed off a clause, when, and on what evidence.
- Slow turnaround, because every wording change is a technical change.
None of this means the core platform’s native capabilities are deficient. Most modern insurance platforms produce documents competently for the transactions they own. The difficulty is that regulated wording rarely respects system boundaries — it spans policy, billing, claims, servicing, and producer communications simultaneously.
Document Complexity Across the Insurance Lifecycle
A governed document layer earns its keep where output variability is high and the data is scattered. Across a typical insurance document lifecycle, that means:
New business and issuance
Application acknowledgements, quote and proposal documents, binders, declarations, policy packets, evidence of coverage, master policies, and ID cards. These pull from rating results, underwriting decisions, and the policy record, then assemble selected forms and clauses in a prescribed order.
Mid-term servicing
Endorsements, certificates, coverage confirmations, and broker correspondence — often triggered ad hoc by a service request rather than by a scheduled process.
Billing and renewal
Invoices, premium increase notices, lapse and cancellation notices, non-renewal notices, and renewal packages. These are frequently high-volume and time-boxed, with statutory notice periods that leave no room for a failed batch to go unnoticed.
Claims
Acknowledgement letters, reservation of rights letters, status updates, settlement correspondence, and denial letters — the documents most likely to be scrutinised later and most likely to depend on precisely the coverage interpretation that reference material informs.
Compliance, audit, and reporting
Required notices, product disclosures, audit reports, statutory and regulatory reporting packages, and filing material.
Each of these varies by jurisdiction, product, distribution channel, language preference, and brand. Multiply those dimensions together and the “template count” problem becomes obvious. The answer is not more templates; it is fewer templates with governed conditional logic, shared clause libraries, and rules that select the right variant at generation time.
Business Ownership Without Losing Control
The most durable argument for a dedicated document layer is not technical. It is about who can safely make a change on a Tuesday afternoon.
Experlogix Document Automation is designed around that premise. Its Template Builder uses familiar Microsoft Word functionality to build policy and correspondence templates with dynamic data fields pulled from connected systems, supporting jurisdiction-specific content, dynamic tables and graphics, and automatic language selection — which removes the need to maintain separate template versions by hand. Content Manager provides a structured, secure repository for digital assets including PDF forms, documents, logos, images, and multimedia, with linked metadata forms, field mapping, and version control. Smart Flows provides the low-code workflow layer with a drag-and-drop builder; Smart Forms handle web-based data capture where information must be gathered rather than retrieved. Across these, actions such as edits, approvals, and timestamps are logged through audit trails, producing a regulator-ready record.
Practically, this draws a clean line. Compliance and operations own wording, clause variants, approval routing, and the trigger conditions that select one variant over another. IT owns integration, identity, environments, monitoring, and release promotion. Neither team is blocked by the other for routine work, and neither loses oversight. In most implementations, IT sets the architecture up once and then empowers business users to run it.
From coverage research to governed documents
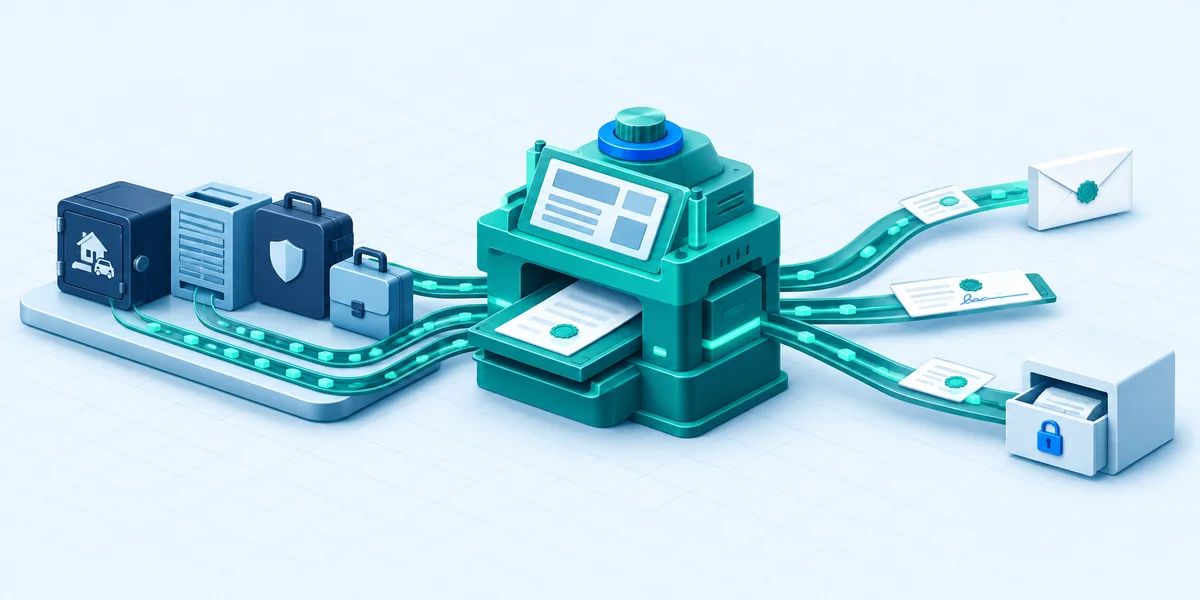
Animation: a draft informed by coverage research cannot go straight into a policy document. Legal and compliance first approve the wording, it is stored as a versioned clause, a template references that clause, and policy, billing and claims documents each use the same wording and record clause version 2.
Integration Architecture: Making Approved Wording Reach the Document
Document generation around a reference-informed wording practice depends on data the reference library never holds. That data lives in the PAS, the claims system, the billing engine, the AMS, the CRM, and sometimes a data warehouse holding the historical book.
The Experlogix Document Automation API is built for exactly this pattern: generation, approvals, delivery, storage, and e-signature steps can be triggered from your own applications and services using straightforward HTTP calls, with a comprehensive library of API actions and role-based API keys that define permissions at the integration level — so responsibilities stay separated and an individual key can be disabled without disrupting other integrations. API integration here is a one-time architectural setup that then carries continuing load: interactive one-off letters during the week, and renewal peaks, mass endorsements, or catastrophe communications when volume spikes. The same interface pattern supports CRM and ERP sources, workflow platforms such as Microsoft Power Automate, content and archive systems including Microsoft SharePoint, and e-signature services such as DocuSign.
A sound data contract for insurance documents should specify, at minimum: the trigger event and its idempotency key; the fields required and their types, including nested structures that need unpacking; calculation and lookup responsibilities; behaviour when a value is missing; the template or template family to select; the jurisdiction, form edition, and effective date to apply; the approval path; the delivery channel and recipient preference; the archive destination and retention rule; and the status reference written back to the originating system.
Equally important is the unhappy path. Duplicate events, retried generations, partially completed batches, delivery failures, and write-back errors all need defined handling and visible monitoring — particularly for statutory notices, where a silent failure is a regulatory event rather than an inconvenience.
AI, Governance, and Human Oversight
Insurance teams increasingly want to ask for a document rather than navigate to it. Experlogix supports this through the Smart Flows MCP server, a Model Context Protocol server published for use in Microsoft Copilot Studio, which lets Copilot agents discover available Smart Flows, query what inputs each requires, trigger execution, track execution state, and retrieve generated documents and their metadata. The agent handles the conversation — gathering and validating inputs before anything is generated. Smart Flows handles structured execution within defined rules.
The governance point is the one that matters for regulated work: every execution triggered through the MCP server runs inside the same Smart Flows security and permissions framework already in place, covering who may run which flows, what gets logged, and how outcomes are tracked. Administrators can monitor execution status, inspect results, and trace generated artefacts using familiar Experlogix tooling even when a flow was started conversationally.
That framing keeps AI in its proper lane. An agent can initiate a governed document workflow. It should not decide coverage, eligibility, pricing, reserve adequacy, or claim outcomes, and it should never be the mechanism by which research commentary becomes customer-facing policy language. Approved content, access controls, logging, and human sign-off remain the control points.
Licensed Content, Approved Wording, and the Line Between Them
A specific caution belongs in any discussion of reference and content providers. Material published by National Underwriter and comparable sources is licensed for professional research and education. Extracting passages into production policy documents raises both licensing and compliance questions, and the two are separate: one concerns your agreement with the publisher, the other concerns whether your regulator and your legal team accept the wording.
A defensible chain looks like this:
- research informs a drafting decision;
- legal and compliance approve specific production wording;
- that approved wording is stored as a governed clause with an owner, a version, an effective date, and an applicable jurisdiction set;
- templates reference the clause rather than embedding a copy of it;
- generated documents record which clause version applied.
Reference material shapes step one. It never becomes step five by itself.
Architectural Trade-Offs Worth Weighing
Combining native platform output with a dedicated document layer is one credible architecture, not the only one.
The honest trade-offs include an additional platform to operate and monitor, a data contract to maintain as source schemas evolve, and a migration exercise for existing templates. Set against those: fewer duplicated templates, a single approval and audit path, reduced custom development, and a lighter dependency on specialist consulting resources for routine wording changes.
Keeping documents native to the core platform is often sensible where output is tightly coupled to a single transaction, volumes are predictable, and the wording rarely changes.
Moving to a centralised document layer tends to pay off where documents span multiple systems, where the same clause must appear identically across policy, billing, claims, and producer communications, where business users need to make frequent controlled changes, or where several cores and legacy books must share one template estate and one brand.
Summary
National Underwriter content helps insurance professionals understand coverage; it does not, and should not, produce the documents that coverage requires. The value is in the chain that follows the research — approval, clause governance, template logic, multi-source data assembly, delivery, evidence, and retention — and that chain is where most insurers still spend disproportionate effort.
For teams evaluating their own position, a practical next step is to map one high-stakes document end to end: pick a cancellation notice or a reservation of rights letter, and record which system supplies each data element, who approves the wording, where the template lives, how jurisdiction and effective date are selected, what proves the document was delivered, and how long the artefact is retained. The gaps in that single map usually tell you whether your document estate needs better governance, better integration, or both — and whether a centralised document layer alongside your existing platforms is the right way to close them.
Frequently Asked Questions
What role does National Underwriter play, and where does document production begin?
National Underwriter sits in the insurance forms and content provider category alongside other research and reference sources that insurance professionals consult daily. Its role is interpretive and educational: helping property and casualty, life, and health professionals understand coverage questions, claims scenarios, regulatory developments, and market practice.
Where does insurance document complexity arise around National Underwriter?
A governed document layer earns its keep where output variability is high and the data is scattered. Across a typical insurance document lifecycle , that means: Application acknowledgements, quote and proposal documents, binders, declarations, policy packets, evidence of coverage, master policies, and ID cards.
Who should own document templates, approvals and governed changes?
The most durable argument for a dedicated document layer is not technical. It is about who can safely make a change on a Tuesday afternoon. Experlogix Document Automation is designed around that premise. Its Template Builder uses familiar Microsoft Word functionality to build policy and correspondence templates with dynamic data fields pulled from connected systems, supporting jurisdiction-specific content, dynamic tables and graphics, and automatic language selection — which removes the need to maintain separate template versions by hand.
How should a governed document layer connect with National Underwriter?
Document generation around a reference-informed wording practice depends on data the reference library never holds. That data lives in the PAS, the claims system, the billing engine, the AMS, the CRM, and sometimes a data warehouse holding the historical book.
How should licensed insurance content be handled before document production?
A specific caution belongs in any discussion of reference and content providers. Material published by National Underwriter and comparable sources is licensed for professional research and education.