Applied Rating Services sits in the part of the distribution chain where speed is most visible: a risk is entered once, premium indications come back from multiple markets, and a producer needs something in a client’s hands quickly. What rating produces is data — carrier, coverage, limits, deductibles, premium, effective dates — and what the client, the carrier and the regulator eventually need is a document: a comparison summary, a proposal, an application packet, a binder request, a certificate, a confirmation letter. The gap between a rated quote and a compliant, on-brand, archived document is where many agencies and brokerages still spend their evenings, rekeying figures into Word files and chasing approvals by email. Left unsolved, that gap slows quote-to-bind cycles, creates version drift across jurisdictions, and makes every small wording change an IT or consulting request.
TL;DR
- Applied Rating Services is a rating capability: its authoritative output is quote and premium data, not a finished client-ready document estate. Document generation, approval, delivery, archiving and evidence usually happen in systems around it.
- The documents that matter most around rating — comparison summaries, proposals, application and submission packets, binder requests, certificates, declination and premium-change letters — typically need data from several sources at once: the rater, the agency management system, the carrier, and the client record.
- Document complexity in this space is less about layout and more about variation: state, province and regional wording, product and carrier differences, form editions, effective dates, mandatory disclosures and preferred language.
- A governed document layer, implemented through API-driven integration, lets operations and compliance own templates and wording while IT retains control of data access, identity, environments and release — reducing dependency on developers and consultants for routine changes.
- Experlogix Document Automation is one way organisations assemble this layer: Microsoft Word-based templates maintained by business users, connections to an unlimited number of data sources, workflow routing with approvals and e-signature participation, audit trails, and an API for embedding generation into existing applications.
Happy shiny people. The industry loves to picture policyholders living their best lives, blissfully unbothered by the catastrophes their cover protects them from — and a centralised document layer that lets business users manage document automation accurately and quickly, without heavy ongoing IT labour, lets the insurance professionals behind those policies live rather well too.
What Applied Rating Services Actually Owns — and What It Doesn’t
Rating services exist to answer a pricing question. Within the Applied Systems ecosystem, Applied Rating Services supports the rating side of agency and brokerage workflow: structured risk and applicant information goes in, carrier premium indications and quote results come back, and those results feed the selling conversation and the eventual submission.
That makes the rater the system of record for a specific and valuable slice of data — quote inputs, quote results, carrier and coverage options, and the state of the submission at a point in time. It is not, and does not try to be, the system of record for the client relationship, the bound policy, the accounting ledger, or the finished document archive. Those sit elsewhere: in the agency management system (AMS), in the carrier’s policy administration system, in the content or archive platform.
Being precise about this boundary matters, because document problems are usually boundary problems. A proposal that must show three carrier options, a loss-run summary, the agency’s professional disclosures and a client’s existing schedule of locations is drawing from at least three systems. Deciding which system owns which element — before any template is built — prevents the familiar outcome where everyone’s spreadsheet is slightly different from everyone else’s.
A practical way to frame it for any workflow around Applied Rating Services:
- Source of truth for each data element (rater, AMS, carrier, CRM, client-supplied form).
- Trigger owner — what event starts document generation (quote completed, option selected, submission ready, bind confirmed).
- Template and wording owner — usually operations and compliance, not IT.
- Approver — who signs off on non-standard wording, premium presentation or coverage commentary.
- Delivery and archive owner — where the final artefact lives and how long it is retained.
- Write-back owner — what status, reference or attachment goes back into the AMS or rating record.
Document Touchpoints Around the Rating Workflow
Rating sits early in the lifecycle, which means the documents around it are disproportionately client-facing and disproportionately time-sensitive. Common touchpoints include:
Each of these has a rhythm. Proposals and binders are interactive and need to be produced in seconds while a client is on the phone. Renewal remarketing arrives in seasonal peaks. Regulatory or carrier-driven form changes arrive without warning and must be applied across every affected template at once.
-
Before submission. Applicant information requests, supplemental questionnaires by line of business, statements of values, driver and vehicle schedules, prior-carrier and loss-history forms. These are intake documents: the quality of what comes back determines how useful the rating output is.
-
At quote. Comparative quote summaries and client proposals that present carrier options side by side, with coverage, limits, deductibles, premium, payment plans and the exclusions that explain a price difference. This is the document most likely to be assembled by hand, and the one where an error is most expensive.
-
At selection and submission. Carrier application packets, signed applications, supplemental forms, coverage-selection and rejection forms where jurisdictions require them, and broker-of-record letters.
-
At bind. Binder requests and binders, evidence of coverage, certificates of insurance, auto ID cards, premium finance agreements, and the confirmation pack the client actually reads.
-
After the quote doesn’t convert. Declination letters, quote-expiry notices, and the follow-up correspondence that keeps a pipeline alive.
-
At renewal and remarket. Renewal comparison summaries, premium-increase explanations, remarketing proposals, coverage-change notices, and the stewardship reports larger commercial clients expect.
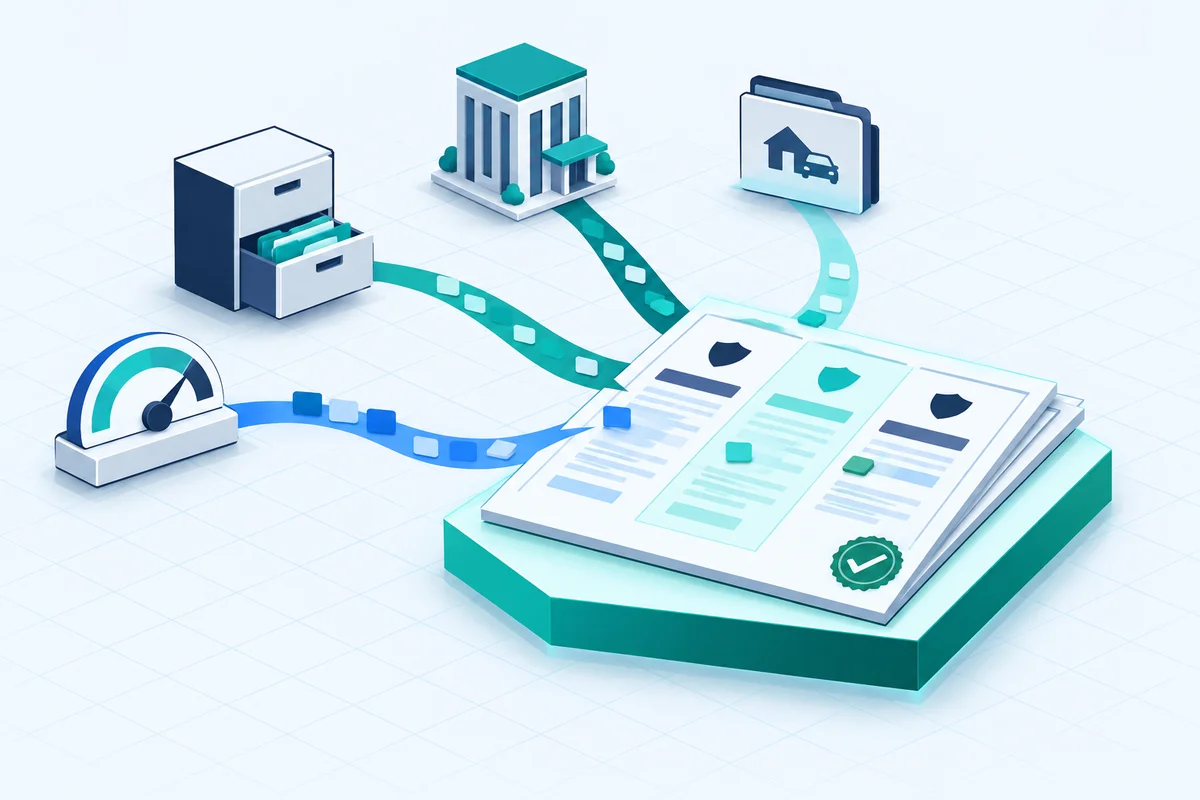
Rated quote → governed document
Premium data from the rater, account data from the agency management system and the client’s schedule merge into one proposal template. A region-specific clause is selected by rule, the document is approved, archived, and a status is written back to the agency management system.
Where Document Complexity Really Comes From
Agencies and brokerages often describe their document problem as "we need nicer proposals". Underneath, it is almost always four problems wearing one coat.
Variation by jurisdiction, product and carrier
The same personal auto proposal needs different disclosures in different states, provinces and regions. Commercial lines multiply this by class of business and carrier appetite. Maintaining a separate document for every permutation is how a template estate quietly grows from twelve files to four hundred, with no reliable way of knowing which is current. Rules-driven templates that select jurisdiction-specific clauses and language automatically are the alternative to maintaining permutations by hand.
Data that cannot be printed as-is
Rating output is structured, and structured data rarely maps one-to-one onto a readable document. Vehicle and location schedules need to be unpacked into tables. Premiums need instalment calculations and comparison deltas. Coverage codes need to be translated into plain-language descriptions. Dates need jurisdictional formatting. In traditional approaches this logic is written as code or script, which is precisely why routine wording changes end up in a developer's backlog. Logic-driven templates that handle conditional content, filtering, calculations and lookups move that work to the people who own the wording.
Form editions and effective dates
If a document has to be reproduced a year later — for an errors and omissions enquiry, an audit, or a coverage dispute — it must reflect the wording and form edition in force at the time, not today's. This is a governance requirement, not a formatting one, and it argues strongly for version control and retained provenance rather than overwritten templates.
Volume with variability
Renewal season, mass remarketing after a carrier withdraws from a class, or catastrophe-related client communications all produce bursts of high-volume generation while interactive proposal production continues. Any architecture should be tested against the peak, not the average, with explicit handling for duplicate triggers, retries, partial batches, missing data and delivery failures. A document that silently fails to generate is worse than one that visibly errors.
Integration Architecture: API-Led, Configured Once, Governed Continuously
The pattern that works around a rating platform is an event-and-API pattern. A business event — quote completed, option selected, submission ready, bind confirmed — becomes a validated trigger. The document layer then retrieves the data it needs under a defined contract, applies rules, selects templates, assembles the output, routes it for approval or signature where required, delivers it, archives it, and writes a status or reference back to the originating record.
API-driven integration is a strength here, not a compromise. It is a one-time setup — increasingly assisted by AI during mapping and configuration — that then provides lasting architectural resilience: it handles volume, it handles multiple sources, and it handles the kind of conditional complexity that insurance documents demand. Experlogix Document Automation provides a flexible API with role-based API keys and an extensive library of API calls, allowing document generation and automation to be embedded into existing applications, and it can connect to an unlimited number of data sources, so a single proposal can combine rating output with agency, carrier and client data without manual consolidation.
Four architectural questions deserve answers before build:
- Identity and access. Which service identities call which systems, and how are they rotated? Role-based permissions and centralised authentication such as single sign-on (SSO) belong in scope from day one.
- Data contract. Which fields are mandatory, what happens when one is missing, and how will schema changes be versioned without breaking live templates?
- Observability. How are generation failures, delivery bounces and incomplete batches detected, reported and reconciled?
- Evidence. What proves which template version, which data, which approver, which delivery channel and which retention rule applied to a given document?
Security and compliance posture matters at this layer too. Experlogix states compliance with SOC 2 and the use of industry standards such as NIST and OWASP guidance in its security practices — the sort of detail an IT or risk reviewer will ask for early.
Business Ownership Without Losing Control
The most durable benefit of a dedicated document layer is organisational rather than technical: the people who understand the wording get to maintain the wording.
Experlogix templates are built using familiar Microsoft Word functionality in a low-code or no-code approach, so operations, marketing and compliance staff can create and amend sophisticated templates — dynamic fields, conditional content, tables, graphics, jurisdiction-specific clauses, language variations — without coding. Smart Forms can be used to collect missing information as part of an automated flow, with a form completion triggering the next document step, which is useful where applicant or supplemental data is needed before a packet can be assembled. Smart Flows handles the routing: who receives what, when, where it is stored, and which approval must happen before release, including integration with Microsoft Power Automate approval processes and SharePoint-based document libraries where organisations already live in the Microsoft estate. E-signature participation through platforms such as DocuSign or Adobe Sign keeps signature capture inside the same workflow.
IT's role shifts rather than shrinks. Security, integration, environments, monitoring and release control stay firmly with IT and architecture; wording, logic and approval paths move to the business. In practice this means a disclosure change in one region becomes an afternoon's work for a compliance analyst rather than a scoped project with external consultants.
This is one architectural approach, not the only one. Where an existing platform's native output already satisfies a document requirement cleanly, leaving it native is a perfectly reasonable decision. The case for a dedicated layer strengthens when documents must combine data from several systems, when the same wording must be reused across multiple platforms and brands, when business users need to make frequent changes, or when evidence and version governance are under regulatory scrutiny.
AI That Assists the Workflow Without Making the Decision
Within that boundary, the useful applications are practical. AI can accelerate template configuration and data mapping during implementation. It can suggest content from approved libraries rather than inventing wording. It can assist review by flagging missing fields or inconsistencies before a packet goes out. And through an agentic interface, a user working in their organisation's AI assistant can ask for a document workflow to be started — "produce the renewal comparison pack for this client" — with the request executing inside the workflow the organisation has already designed.
Experlogix Document Automation includes the Smart Flows MCP (Model Context Protocol) server, built on an emerging standard that allows AI agents — for example, agents built in Microsoft Copilot Studio — to connect to existing systems in a structured, auditable way. Agents can discover which Smart Flows are available, gather and validate the required inputs, initiate execution, track status and return the generated documents, giving agents the context to act while giving the organisation the governance layer to define exactly how they act. Every document generated is traceable and every agent action is logged, which is the precondition for using AI anywhere near regulated communications. Human oversight, approved content, access controls and provenance are not optional extras here; they are what makes the productivity gain defensible when someone asks how a document came to exist.
AI is genuinely useful in this space, and genuinely risky if the boundary is drawn carelessly. The safe and productive boundary is simple: AI may assist with assembling, reviewing and initiating document work; it does not make underwriting, pricing, eligibility or coverage decisions. Those remain with authorised people and authorised systems — the carrier, the underwriter, the rating rules.
The Wider Ecosystem Around Rating
Rating rarely operates alone. In most agency and brokerage environments, Applied Rating Services sits alongside an agency management system such as Applied Epic, carrier portals and policy administration platforms, a CRM, an e-signature service, and a content or archive repository such as Microsoft SharePoint. Microsoft Power Automate frequently provides the connective workflow tissue where the organisation is Microsoft-centric.
A governed document layer earns its keep precisely because it spans these. One template estate, one set of brand and compliance rules, and one workflow engine can serve documents triggered from the rater, from the AMS, and from the carrier-facing processes — rather than three disconnected sets of templates that drift apart within a year. For multi-brand or multi-location organisations, that centralisation is often the difference between consistent client communications and a well-intentioned free-for-all.
Summary
Applied Rating Services does what it is designed to do: produce reliable rating and quote data quickly. The opportunity for most agencies, brokerages and programme operators is not to change that, but to improve what happens immediately afterwards — the document generation, approval, delivery, archiving and evidence that turn a rated quote into something a client can act on and an auditor can trace.
Three considerations should shape any evaluation. First, map ownership explicitly: source of truth, trigger, template, approver, delivery, archive and write-back. Second, design for variation and failure, not just the happy path — jurisdictional wording, form editions and effective dates on one side; missing data, duplicate triggers, retries and partial batches on the other. Third, decide deliberately where business ownership should sit, because a template estate that only IT or an external consultant can change will always move at the speed of a backlog.
A sensible next step is small and concrete: pick the single highest-volume document around your rating workflow — usually the client proposal or the renewal comparison pack — document every data element it needs and where that element truly lives, and time how long a wording change currently takes from request to live use. Those two artefacts will tell you more about whether a centralised document layer is worth building than any feature comparison will.
Frequently Asked Questions
What role does Applied Rating Services play, and where does document production begin?
Rating services exist to answer a pricing question. Within the Applied Systems ecosystem, Applied Rating Services supports the rating side of agency and brokerage workflow: structured risk and applicant information goes in, carrier premium indications and quote results come back, and those results feed the selling conversation and the eventual submission.
Which document workflows extend around Applied Rating Services?
Rating sits early in the lifecycle, which means the documents around it are disproportionately client-facing and disproportionately time-sensitive. Common touchpoints include: Each of these has a rhythm. Proposals and binders are interactive and need to be produced in seconds while a client is on the phone.
Where does insurance document complexity arise around Applied Rating Services?
Agencies and brokerages often describe their document problem as "we need nicer proposals". Underneath, it is almost always four problems wearing one coat.
How should a governed document layer connect with Applied Rating Services?
The pattern that works around a rating platform is an event-and-API pattern. A business event — quote completed, option selected, submission ready, bind confirmed — becomes a validated trigger. The document layer then retrieves the data it needs under a defined contract, applies rules, selects templates, assembles the output, routes it for approval or signature where required, delivers it, archives it, and writes a status or reference back to the originating record.
Who should own document templates, approvals and governed changes?
The most durable benefit of a dedicated document layer is organisational rather than technical: the people who understand the wording get to maintain the wording. Experlogix templates are built using familiar Microsoft Word functionality in a low-code or no-code approach, so operations, marketing and compliance staff can create and amend sophisticated templates — dynamic fields, conditional content, tables, graphics, jurisdiction-specific clauses, language variations — without coding.